How to Choose the Best High-Yield Savings Account in 2026
If you are keeping your emergency fund or down payment savings in a traditional brick-and-mortar bank, you are likely earning a paltry 0.01% Annual Percentage Yield (APY). Meanwhile, online banks offering High-Yield Savings Accounts (HYSAs) are paying over 400x that amount for the exact same level of risk. In 2026, there is no excuse to leave free money on the table.
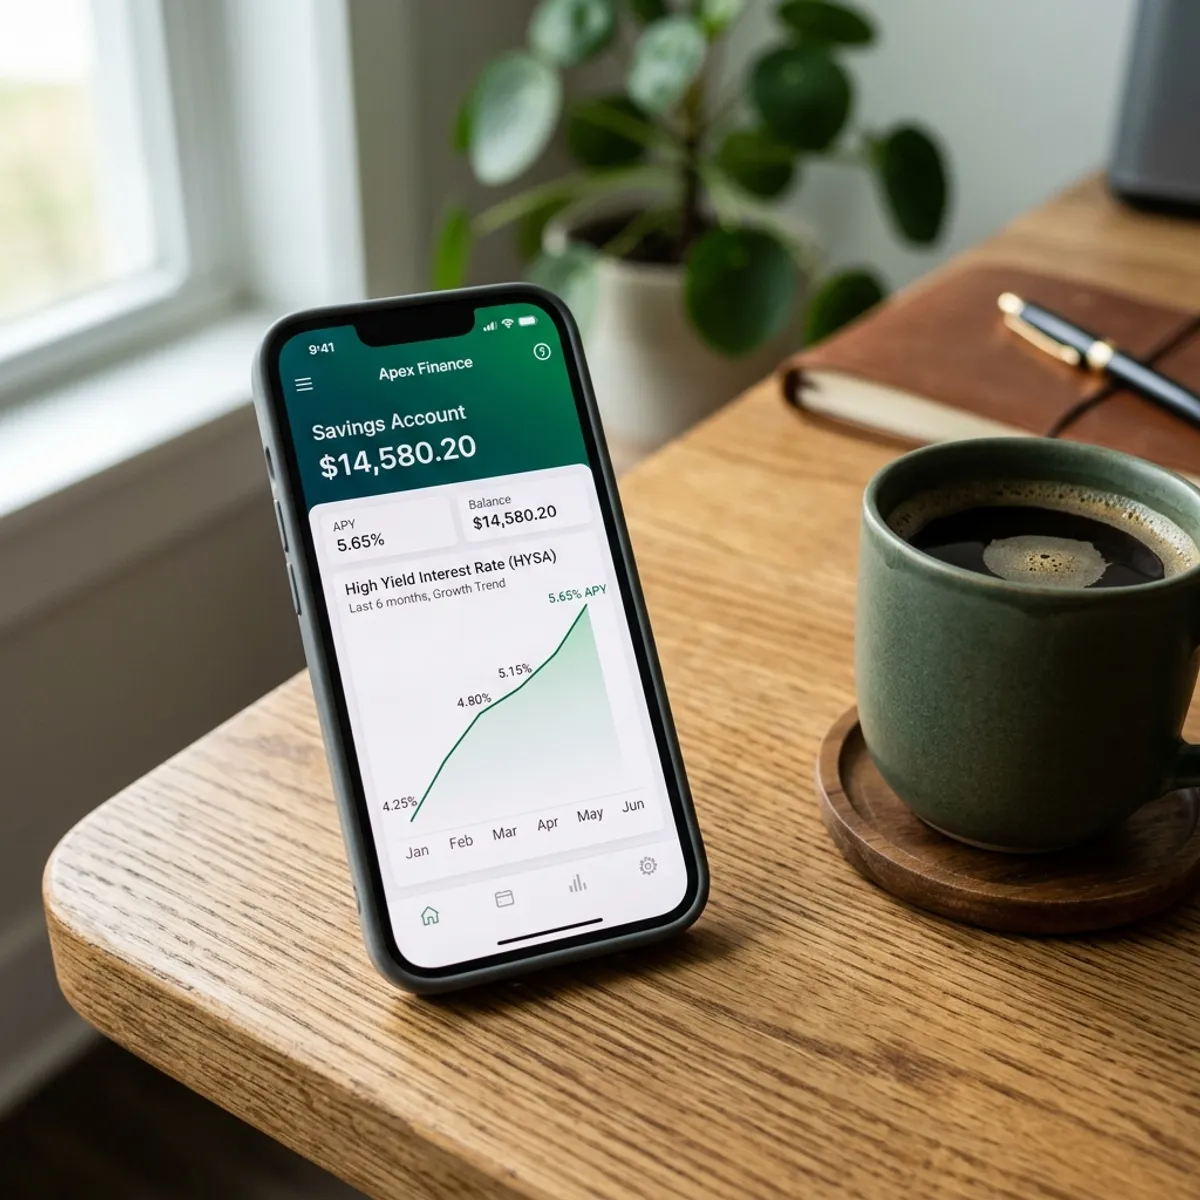
1. The Mechanics of a High-Yield Savings Account
A High-Yield Savings Account functions identically to a standard savings account, with one critical distinction: the interest rate it pays on your deposits. This disparity is entirely structural. Traditional national banks operate thousands of physical branches, employ tens of thousands of tellers, and maintain massive real estate footprints. Their overhead costs are astronomical.
Online-only banks operate without this physical infrastructure. They maintain servers and customer support centers, but lack retail branches. To attract deposits away from established national chains, online banks pass their operational savings directly to the consumer in the form of a significantly higher APY.
When you deposit money into an online HYSA, the bank utilizes those funds to issue auto loans, mortgages, or simply deposits them at the Federal Reserve to earn a baseline yield. They capture a margin, and you receive a competitive, risk-free return.
2. The Mathematics of Compounding Interest
The difference between a 0.01% APY and a 5.00% APY is not a minor optimization; it is a fundamental shift in wealth accumulation. To illustrate this, consider an emergency fund containing $20,000.
If left in a traditional savings account at 0.01%, that $20,000 will generate exactly $2.00 in interest over 12 months. Over 5 years, assuming no additional contributions, the total interest earned is $10.00.
If that same $20,000 is transferred to a 5.00% HYSA, it generates $1,000 in the first year alone. Because the interest compounds, the balance at the end of year one is $21,000. In year two, you earn 5.00% on $21,000, yielding $1,050. Over a 5-year period, this account generates over $5,525 in free capital, bringing the total balance to $25,525.
3. The Four Mandatory Features of a Top-Tier HYSA
When evaluating different online banks in 2026, do not simply select the institution advertising the highest interest rate. Ensure the account meets four non-negotiable criteria:
- Federal Insurance: The bank must be insured by the Federal Deposit Insurance Corporation (FDIC) or the National Credit Union Administration (NCUA). This guarantees that your deposits are protected up to $250,000 per depositor, per institution, in the event of a bank failure.
- Zero Monthly Maintenance Fees: The primary purpose of a HYSA is to accumulate money. Accept zero monthly fees. The best online banks do not charge you to hold your money.
- No Minimum Balance Requirements: You should receive the advertised APY whether your balance is $100 or $100,000. Avoid accounts that require a $10,000 minimum to unlock the highest tier.
- Rapid Transfer Speeds: Since you cannot visit a physical branch to withdraw cash, the bank must support fast ACH transfers. You should be able to push money to your primary checking account within 1 to 3 business days.
4. The Impact of the Federal Reserve on HYSA Rates
The APY on a High-Yield Savings Account is variable, meaning it can change at any time without prior notice. This fluctuation is directly tied to the Federal Reserve's target federal funds rate.
When the Federal Reserve raises interest rates to combat inflation, it becomes more expensive for banks to borrow money. Consequently, banks raise the yields on savings accounts to attract consumer deposits, which they use to fund their lending operations. Conversely, when the Federal Reserve cuts rates to stimulate the economy, online banks will quickly reduce the APY on their savings products.
If you desire a fixed, guaranteed rate for a specific duration (e.g., 12 or 24 months), you must lock your money into a Certificate of Deposit (CD). For a detailed breakdown of this tradeoff, see our guide on HYSA vs. CD.
5. Tax Implications of High-Yield Savings
While the interest earned in a HYSA is entirely passive and carries zero market risk, it is not tax-free. The United States government classifies interest generated from bank accounts as ordinary taxable income.
At the conclusion of the tax year, any financial institution that paid you more than $10 in interest will issue a Form 1099-INT. You are required to report this amount on your annual tax return, and it will be taxed at your marginal income tax rate. For official guidelines regarding taxable interest, consult the IRS Tax Topic 403.
6. Common Pitfalls and Hidden Rules
Before opening an account, carefully review the fine print to avoid common industry pitfalls. Some institutions advertise a "teaser rate" that applies only for the first three months, after which the APY drops significantly.
Furthermore, be aware of withdrawal limits. Historically, Federal Regulation D limited savings account withdrawals to six per month. While the Federal Reserve indefinitely suspended this requirement in 2020, many banks still enforce their own internal limits and may charge a fee if you transfer money out of your HYSA more than six times in a single statement cycle.
Frequently Asked Questions (FAQs)
Do I have to switch my checking account too?
No. You can keep your primary checking account at your current local bank and simply link your new online HYSA to it via routing and account numbers. Keeping them at separate institutions is a highly recommended budgeting strategy, as it creates friction and removes the temptation to spend your savings.
Is my money locked in a High-Yield Savings Account?
No. Unlike a Certificate of Deposit (CD), the funds in a HYSA remain highly liquid. You can deposit or withdraw your money at any time without penalty, though you may be subject to the bank's monthly transaction limits.
How is the interest calculated and paid?
Most HYSAs calculate interest daily based on your current balance and pay it out monthly. When the interest is deposited into your account at the end of the month, it immediately begins earning interest itself, creating a compounding effect.
