Credit Card Payoff Calculator
Credit card interest is designed to trap you in debt. Use this calculator to see how long it will actually take to pay off your balance, and how much interest the bank is making off you.
Based on your fixed monthly payment.
Balance Burn Down
How We Calculate This
This calculator simulates paying your credit card off using accurate monthly amortization, which mirrors exactly how your bank calculates your interest charges.
Note: If you use the "I Know My Payment" mode, and your payment is less than the Monthly Interest Charge, the calculator will warn you that your balance is growing infinitely.
How to Escape Credit Card Debt (The Mathematical Truth)
Credit cards are designed to keep you in debt for as long as possible. The banks use the magic of compound interest against you. Here is exactly how they do it, and the mathematical steps you must take to break free. If you are struggling with minimum payments, read the advice provided by the Consumer Financial Protection Bureau.
The Minimum Payment Trap
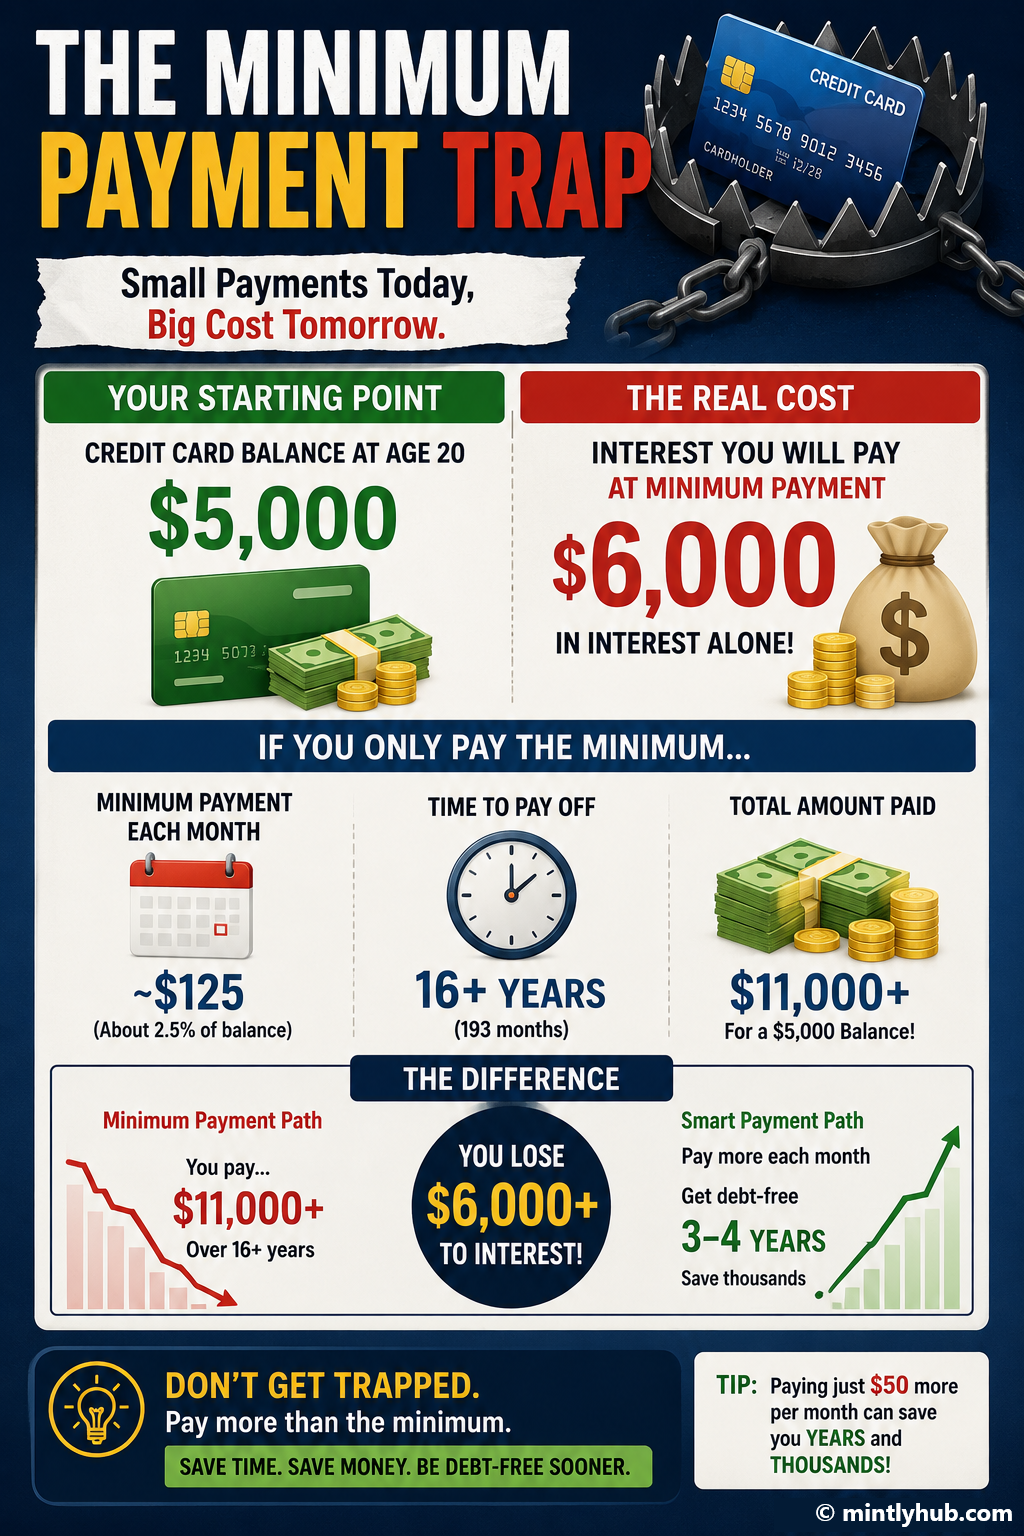
If you look at your credit card statement, the bank prominently displays the "Minimum Payment Due." This number is usually calculated as 1% to 2% of your total balance, plus the interest charged that month.
Paying the minimum is exactly what the bank wants you to do.
Example: $5,000 Balance at 24% APR
- If your minimum payment is $150/month...
- It will take you 54 months (4.5 years) to pay it off.
- You will pay $3,000 in pure interest to the bank.
- You effectively paid $8,000 for $5,000 worth of goods.
Every dollar you pay above the minimum goes directly toward your principal balance, instantly reducing the interest you will be charged the next month.
How Credit Card Interest is Calculated
Credit card interest doesn't just accumulate monthly—it actually compounds daily. This is why credit card debt spirals out of control faster than student loans or mortgages.
To figure out how much you are being charged, divide your APR by 365. This gives you your Daily Periodic Rate (DPR). The bank multiplies this rate by your balance every single day.
Roughly speaking, on a 24% APR card, you are being charged 2% of your balance in interest every month. If you have a $10,000 balance, you are generating $200 in interest charges every 30 days. If your payment is $250, only $50 is actually paying down the debt.
Use our Credit Card Payoff Calculator to see exactly how much of your payment is being eaten by interest.
The Danger of Negative Amortization
Negative amortization occurs when your monthly payment is less than the interest charge for that month.
For example, if your interest charge is $200, but you only make a $150 payment, your balance grows by $50. Next month, you are charged interest on a higher balance, which means the interest charge increases to $201.
The 2 Best Payoff Strategies
If you have multiple credit cards, do not just spread your extra cash evenly across all of them. That is the slowest way to get out of debt. You must use a targeted strategy.
The Debt Snowball (Psychology First)
Pay minimums on everything, and put all your extra cash toward the card with the smallest balance, regardless of the interest rate. When that card is paid off, take that payment and roll it into the next smallest balance. This gives you quick psychological wins. See our Snowball Calculator.
The Debt Avalanche (Math First)
Pay minimums on everything, and put all extra cash toward the card with the highest interest rate (APR). Mathematically, this saves you the most money and pays the debt off the fastest, but it can be harder to stick to if your highest interest card is also your largest balance.
When to Consider Consolidation
If your APR is over 20% and you have good credit, you should immediately look into lowering your interest rate so your payments actually go toward the principal.
- 0% Balance Transfer Card: Many banks will give you 12 to 18 months of 0% interest if you transfer your debt to them. (They usually charge a 3% fee to do this). If you use this, you must pay off the debt before the 0% period ends, or the high interest kicks back in.
- Personal Loan: You can take out a fixed personal loan at 10% to 12% to pay off your 25% credit cards. See our Refinance Calculator to compare the savings.
Bottom Line
To get out of credit card debt, you have to drastically increase your payments above the minimum. Use our calculator in "Target Date" mode to see exactly how much you need to pay every month to be debt-free in 1 or 2 years.
✅ What to do next? (Your Action Plan)
Seeing the numbers can feel overwhelming, or it might spark motivation. Either way, here are three tiny, emotionally safe steps you can take today:
- Save your baseline: Screenshot these results or write them down. You now have a concrete starting point, which is the hardest part of any financial journey.
- Read the methodology: Understanding the math will remove the fear of the unknown. Scroll up to the "How to Use Guide" or explore our Glossary to understand exactly what these numbers mean.
- Take a 5-minute win: Pick one tiny action you can do right now from your phone—like logging into your bank to check a balance, setting a calendar reminder for tomorrow, or reading a related article.
