Monthly Budget Calculator
Stop wondering where your money went. Enter your monthly income and expenses below to instantly see your free cash flow and where you can cut back.
This is money you can use to crush debt or boost savings.
Where Is Your Money Going?
How to Budget (And Actually Stick to It)
Budgeting feels restrictive, which is why most people hate it. But a budget isn't about restricting your money—it's about telling your money where to go instead of wondering where it went. Here is the step-by-step framework to build a budget you can actually stick to. To apply these concepts directly, use our monthly budget calculator and review budgeting for beginners: a complete 2026 guide. You might also find our guide on the ultimate guide to side hustle taxes in 2026 helpful. You can find additional budgeting resources and worksheets at the Consumer Financial Protection Bureau (CFPB).
Step 1: Calculate Your Real Income
Do not budget based on your salary. Budget based on your Take-Home Pay.
If you make $60,000 a year, your monthly income is technically $5,000. But after federal taxes, state taxes, health insurance, and 401(k) contributions are pulled out of your check, your actual take-home pay might only be $3,800.
Always use the exact amount of money that actually hits your checking account every month. If your income fluctuates because you are a freelancer or work for tips, calculate your average income over the last 3 months and subtract 10% to be safe.
Step 2: List Your Fixed Expenses
Fixed expenses are bills that cost the exact same amount every single month. These are the easiest to budget for because there are no surprises.
- Housing: Rent or Mortgage (including property tax & insurance)
- Transportation: Car payment and auto insurance
- Utilities: Internet, cell phone, trash, water
- Debt: Minimum student loan and credit card payments
- Subscriptions: Netflix, gym memberships, software
Step 3: Estimate Variable Expenses
This is where budgets fail. Variable expenses fluctuate every month. You cannot predict them perfectly, so you have to estimate them based on your past habits.
- Groceries & Dining Out: Look at your bank statements for the last two months. How much did you actually spend on food? Be brutally honest.
- Gas/Fuel: How much do you drive?
- Shopping & Entertainment: Clothes, hobbies, movies, concerts.
- Miscellaneous: Haircuts, household supplies, pet food.
When you put these numbers into our Budget Calculator, do not put the number you wish you were spending. Put the number you are actually spending right now. We will optimize it in Step 4.
Step 4: Find Your Free Cash Flow
Once you have your Income and your Expenses, subtract the two.
Income - Expenses = Cash Flow
- If Positive (Leftover Money): Great! You now have a job to give this money. Allocate this leftover cash toward building an Emergency Fund, paying off high-interest debt, or investing for retirement.
- If Negative (Over Budget): Red Alert. You are spending more than you earn. This difference is quietly being added to your credit card balance every month. You must immediately cut variable expenses (dining out, shopping) until this number is positive.
Popular Budgeting Methods Compared
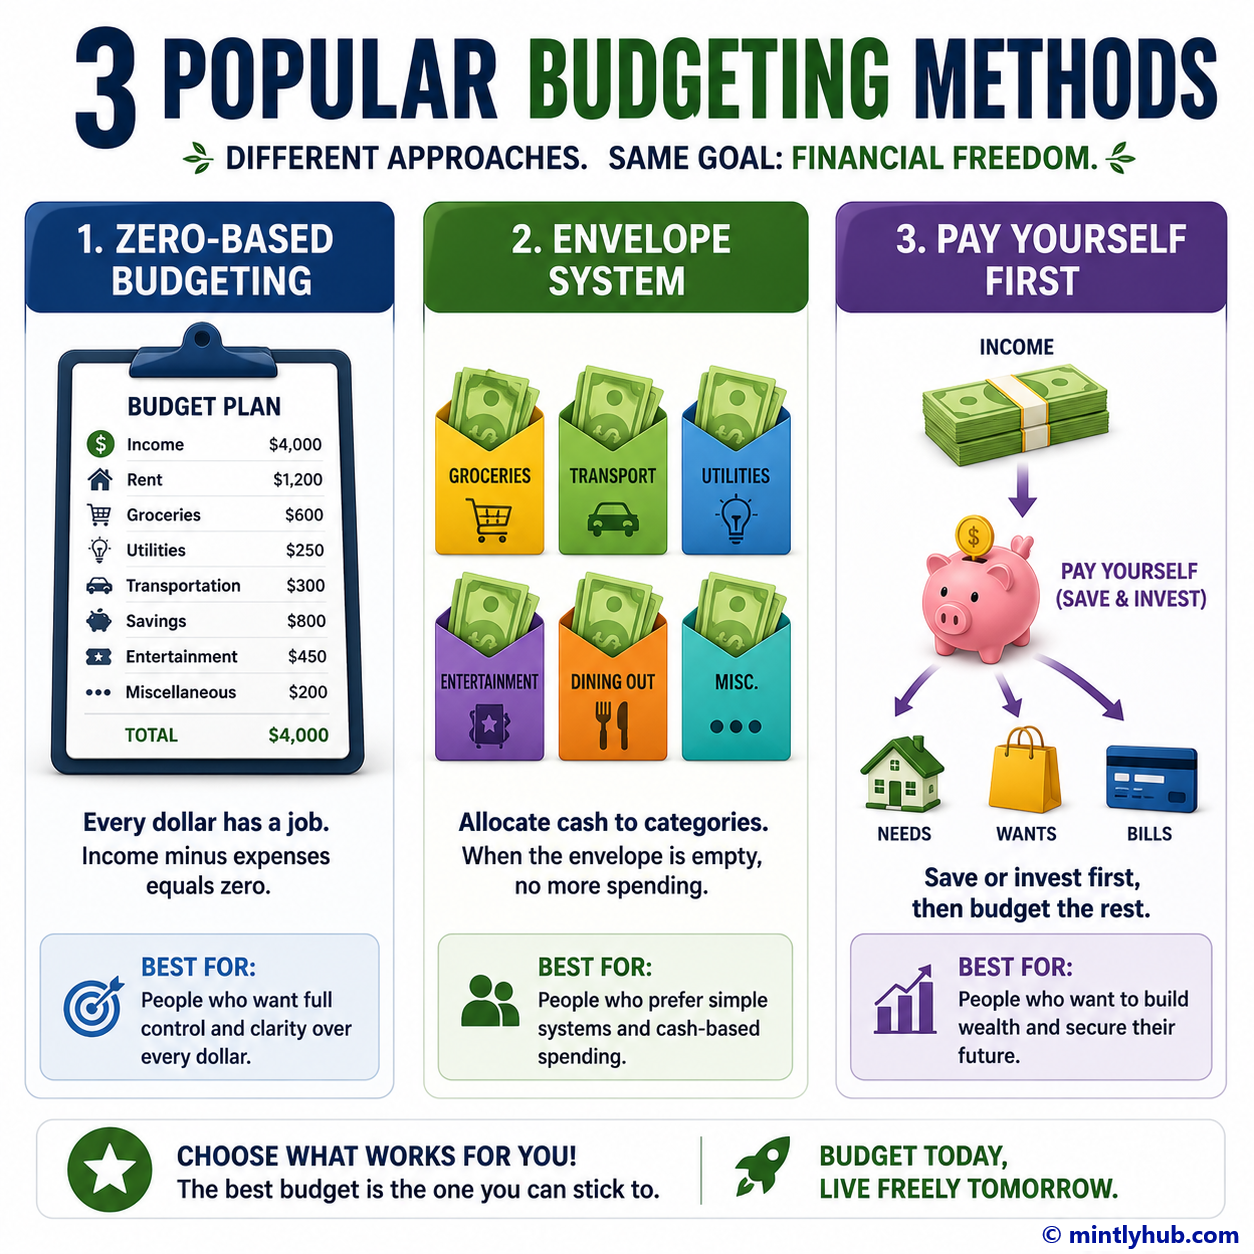
There is no "perfect" way to budget. The best method is the one you will actually stick to. Here are the three most popular frameworks:
| Method | How it Works | Best For... |
|---|---|---|
| The 50/30/20 Rule | 50% Needs, 30% Wants, 20% Savings. | Beginners who want a simple, balanced rule of thumb. |
| Zero-Based Budgeting | Every dollar is assigned a specific job until you have exactly $0 left to allocate. | Detail-oriented people who want maximum control over their money. |
| Pay Yourself First | Automate 20% to savings immediately on payday. Spend the rest however you want. | People who hate tracking spreadsheets and just want to automate their wealth. |
Bottom Line
Budgeting takes about 2 hours to set up the first time, and then 15 minutes a month to maintain. That 15 minutes a month is the difference between retiring wealthy and living paycheck to paycheck forever.
✅ What to do next? (Your Action Plan)
Seeing the numbers can feel overwhelming, or it might spark motivation. Either way, here are three tiny, emotionally safe steps you can take today:
- Save your baseline: Screenshot these results or write them down. You now have a concrete starting point, which is the hardest part of any financial journey.
- Read the methodology: Understanding the math will remove the fear of the unknown. Scroll up to the "How to Use Guide" or explore our Glossary to understand exactly what these numbers mean.
- Take a 5-minute win: Pick one tiny action you can do right now from your phone—like logging into your bank to check a balance, setting a calendar reminder for tomorrow, or reading a related article.
