Dividend Income Calculator
Calculate how your passive income will grow over time through dividend yields and the power of Dividend Reinvestment Plans (DRIP).
Quick Breakdown
How This Calculator Works
This tool uses compound interest formulas to project stock appreciation and dividend yields over time.
Dividend Calculator Guide: How DRIP & Yield Compound Wealth
Understanding the math behind dividend investing is crucial for building a sustainable passive income portfolio. This guide explains how to use our calculator to project your future income and why reinvesting your dividends is one of the most effective strategies for building wealth.
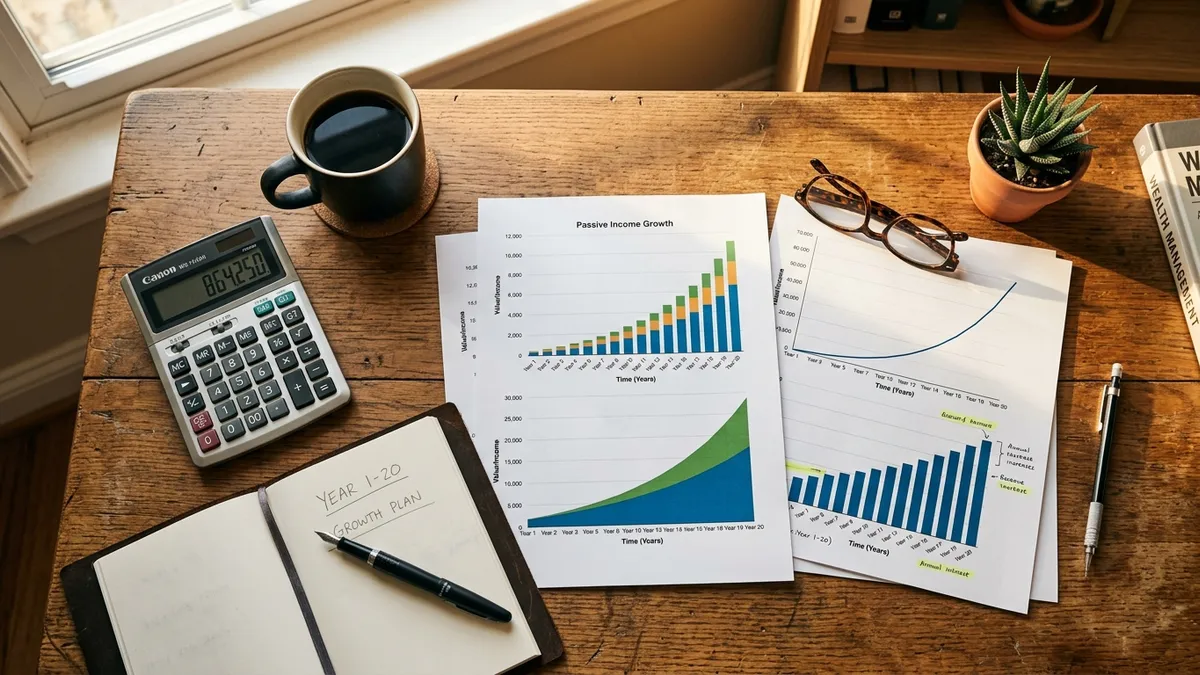
The Mechanics of Dividend Reinvestment Plans (DRIP)
A Dividend Reinvestment Plan (DRIP) is an automated setup where the cash dividends paid out by a company or ETF are immediately used to purchase more shares of that same asset. When you utilize a DRIP, your investment portfolio can grow steadily without requiring active trading on your part.
Without DRIP, your dividends sit in your brokerage account as cash. While taking cash payouts provides immediate liquidity, it halts the compounding effect of your dividends. Compounding relies on the principle that your earnings generate their own earnings over time.
Example: $10,000 at 4% Yield over 20 Years
- Without DRIP (Cash Payouts): You collect $400 every year. Over 20 years, you collect $8,000 in total dividends. Your original $10,000 principal remains $10,000.
- With DRIP: In year 1, your $400 buys more shares. In year 2, you earn 4% on $10,400. After 20 years, your total balance is $21,911. Your annual dividend payout has grown to $876/year without you ever adding a single new dollar.
Yield on Cost (YOC) Explained
As you hold a dividend-paying stock for a long time, the company will hopefully increase its dividend payout per share. "Yield on Cost" is a metric that shows your current dividend yield relative to the original price you paid, not the current market price.
For example, if you purchase a stock for $100 that pays a $3 dividend, your yield is 3%. If, ten years later, the stock pays a $9 dividend, your Yield on Cost is now 9%, because you only paid $100 for those original shares. This metric helps long-term investors evaluate the growing income stream from their early investments, highlighting the benefits of holding solid companies through various market cycles.
Understanding the Mathematics Behind the Calculator
Our dividend calculator uses a combination of basic compounding formulas to project your future portfolio value. The calculator takes into account your initial principal, your expected annual dividend yield, your expected annual share price appreciation, and your ongoing contributions.
The core formula for compound growth with regular contributions involves calculating the future value of a series. When you enable DRIP, the calculator assumes that every dividend payment is seamlessly reinvested at the current share price, increasing your share count for the next payout period. This is similar to how the SEC explains compound interest, where time and rate of return heavily influence the final balance.
Imagine an investor starting with a modest $5,000 initial investment in an index fund that yields 3% annually in dividends, with an expected 5% annual price growth. If this investor contributes $200 per month and reinvests all dividends, the calculator will show how the share count steadily climbs. By year 15, the dividend income alone will often exceed the original monthly contributions, demonstrating the shift from active saving to passive income generation.
Beware the "Yield Trap"
When projecting future income, it might be tempting to enter a 12% expected dividend yield to see massive returns. In reality, exceptionally high dividend yields are often "Yield Traps." A yield trap occurs when a company's stock price crashes, which mathematically pushes the yield percentage up, often because the market anticipates the company to cut its dividend or face severe financial trouble.
Focusing entirely on high yields can lead to significant principal losses. Financial experts advise aiming for sustainable yields, typically in the 2% to 5% range. Sustainable dividends come from companies with strong free cash flow and a history of consistent payouts, rather than distressed businesses artificially maintaining a high yield to attract investors. For more insights on steady growth, review our guide on index funds.
Input Explanations: Making the Most of the Calculator
To accurately forecast your dividend income, you must provide realistic inputs. Here is a breakdown of the key fields:
- Initial Investment: The starting amount of capital you plan to allocate to dividend-paying assets.
- Expected Annual Yield: The percentage of the stock's current price that the company pays out in dividends each year. Using historical averages for the broader market or specific dividend ETFs provides the most accurate baseline.
- Expected Annual Stock Price Growth: Aside from dividends, this represents how much the underlying stock price increases. A standard estimate for a diversified portfolio is around 5% to 7% post-inflation.
- Years to Grow: The time horizon for your investment. Due to the nature of exponential growth, increasing this number by even five years can double the final output.
Consider someone five years away from retirement who has $100,000 saved and plans to shift towards a dividend income strategy. By inputting a realistic 4% yield and stopping DRIP at the five-year mark, the calculator clearly illustrates the transition from the accumulation phase to the distribution phase, showing exactly how much cash flow will be available to cover living expenses.
How to Maximize Your Calculator Projections
Proper planning allows you to optimize your investment strategy. Following a few strict principles can enhance the outcome of your portfolio.
- Start Early: The most critical variable in the calculator is "Years to Grow." Compounding is back-loaded; the most significant financial gains materialize in the final years of the investment horizon.
- Toggle DRIP On: Always select "Yes, reinvest dividends" during your accumulation phase. This guarantees your share count continues to increase automatically.
- Add Annual Contributions: Relying on the starting principal alone often leads to slow progress. Adding consistent monthly or annual contributions drastically alters the trajectory of your final portfolio value.
By understanding the mathematics and avoiding common pitfalls, you can use dividend projections to build a robust financial plan.
Go to the Dividend Calculator +✅ What to do next? (Your Action Plan)
Seeing the numbers can feel overwhelming, or it might spark motivation. Either way, here are three tiny, emotionally safe steps you can take today:
- Save your baseline: Screenshot these results or write them down. You now have a concrete starting point, which is the hardest part of any financial journey.
- Read the methodology: Understanding the math will remove the fear of the unknown. Scroll up to the "How to Use Guide" or explore our Glossary to understand exactly what these numbers mean.
- Take a 5-minute win: Pick one tiny action you can do right now from your phone—like logging into your bank to check a balance, setting a calendar reminder for tomorrow, or reading a related article.
