What is APY? (Annual Percentage Yield & Compounding Explained for 2026)
When you place cash into deposit vehicles such as a High-Yield Savings Account (HYSA), a Certificate of Deposit (CD), or a Money Market Account in 2026, the vital number dictating your financial growth is the APY (Annual Percentage Yield). Unlike simple interest rates, APY represents the total real percentage of yield you will earn over a full 365-day year, explicitly accounting for the wealth-accelerating engine of **compound interest**. When interest compounds daily or monthly, you do not simply earn interest on your original deposit; you continuously earn interest on your previously accumulated interest! Here is how banking algorithms compute APY and how to harness compounding to accelerate your passive returns.
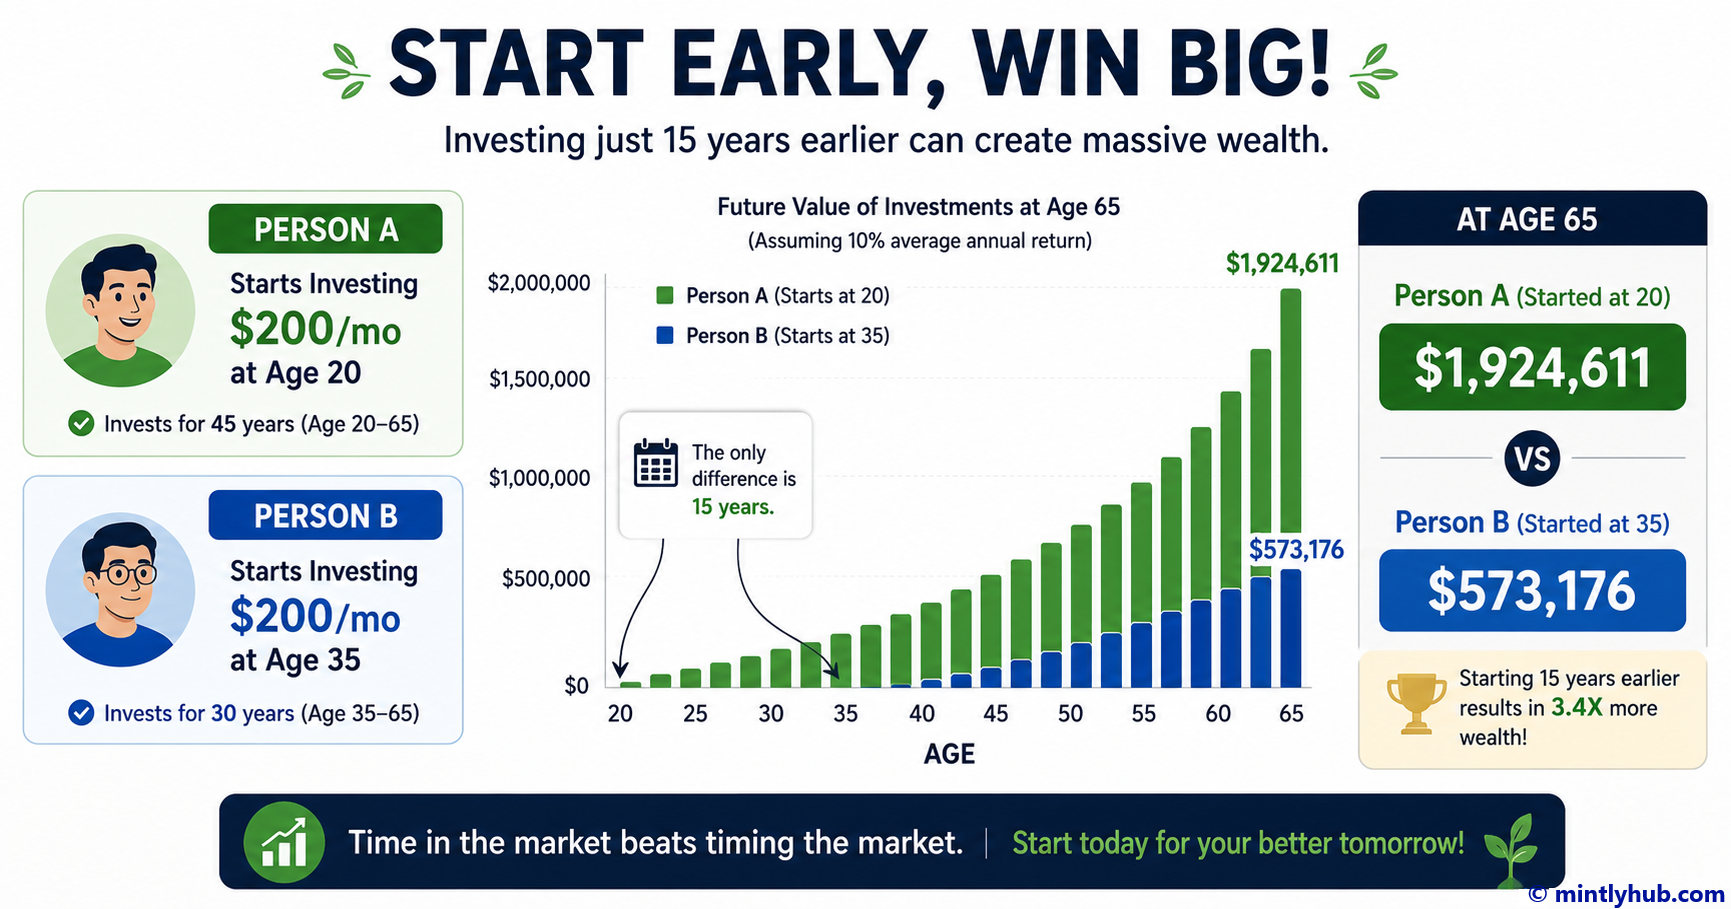
⚡ Action Checklist: 4 Proven Strategies to Maximize Your APY
Never let cash sit in stagnant traditional brick-and-mortar savings accounts earning 0.01% APY. Apply these yield maximization steps:
- ✔Switch to an Online High-Yield Savings Account: Online banks operating without physical branch overhead routinely offer APYs that are **400x to 500x higher** than legacy national megabanks.
- ✔Confirm Daily Interest Compounding Frequency: Always verify that your bank compounds interest *daily* rather than quarterly or yearly; faster compounding intervals generate slightly higher real dollar yields.
- ✔Build a CD Ladder for Guaranteed APY Lock: Because savings APYs are variable, lock in high promotional yields for 1 to 5 years using structured Certificates of Deposit during peaking interest rate environments.
- ✔Verify FDIC or NCUA Federal Insurance: Only deposit your wealth into financial institutions holding verified federal insurance, shielding your cumulative APY deposits up to $250,000 against institution failure.
1. How APY Differs from Simple Interest (The Math of Compounding)
To fully appreciate the architectural brilliance of APY, you must examine how it builds upon nominal **Simple Interest**. If a conventional bank advertises a simple nominal interest rate of 5.00%, that percentage solely measures interest calculated against your initial starting principal.
In contrast, APY leverages mathematical exponentiation to reflect compounding frequency. Under federal banking regulations monitored by the Federal Deposit Insurance Corporation (FDIC) and the Federal Reserve, banks compute APY using a universal statutory formula:
APY = (1 + r / n)n − 1
In this financial equation, r represents the nominal stated interest rate as a decimal, and n represents the number of compounding periods per year (365 for daily compounding, 12 for monthly compounding). Because daily compounding repeatedly reinvests microscopic earnings every single midnight, a nominal interest rate of 5.00% automatically converts into an official APY of 5.13%!
📊 Real-Life Case Study: Brian’s $25,000 Emergency Fund Breakthrough
Brian keeps his $25,000 cash reserve inside an old traditional bank savings account paying a minimal simple interest rate of 0.01% APY. After consulting an accredited financial planner in 2026, he transfers the entire balance into an online High-Yield Savings Account offering **5.00% APY compounded daily**. Let's compare his passive cash earnings over a 3-year timeline without adding a single penny of new money:
Old Mega-Bank at 0.01% APY
• Starting Balance: $25,000
• Compounding Effect: Practically Zero
• Total Interest Earned after 3 Years: $7.50
• Result: Inflation completely destroyed Brian's cash purchasing power!
Online HYSA at 5.00% APY (Daily Compounding)
• Starting Balance: $25,000
• Compounding Effect: Exponential Daily Growth
• Total Interest Earned after 3 Years: +$3,948.35!
• Result: Brian passively generated nearly $4,000 in free taxable income!
Takeaway: Harnessing daily compounding through high APY accounts transforms idle emergency cash from a depreciating liability into an actively performing cash flow engine.
2. Variable APY vs. Fixed APY (HYSAs vs. CDs)
When deploying liquid funds across the banking sector in 2026, borrowers must understand whether their contractual yield is dynamic or locked:
- Variable APY (High-Yield Savings & Money Markets): The advertised APY can float up or down at any moment based on central Federal Reserve rate adjustments. If inflation cools and macro borrowing benchmarks decline, your HYSA yield will experience downward rate resets. However, you maintain absolute liquidity and can withdraw cash anytime without penalty.
- Fixed APY (Certificates of Deposit - CDs): When you purchase a 12-month or 36-month Certificate of Deposit, your bank legally guarantees your advertised APY for the entire contractual duration regardless of macro rate drops. The tradeoff is strict illiquidity: withdrawing capital prior to maturity triggers costly penalty withdrawals forfeiting months of earned compounding interest.
Explore how to properly balance liquid emergency reserves versus locked investments in our breakdown on High-Yield Savings Accounts vs. CDs, or simulate multi-decade compounding schedules using our free Certificate of Deposit Calculator and Compound Interest Wealth Calculator.
Frequently Asked Questions (FAQ)
Why is APY always higher than the stated base interest rate?
Your base nominal interest rate represents simple interest calculated solely against your starting balance without factoring in timing intervals. Because almost all modern consumer savings vehicles compound interest either daily or monthly, each small interest credit immediately adds to your primary deposit base, creating a progressively larger sum for the subsequent period. APY captures this compounding acceleration, making it consistently higher than the nominal rate.
Do I have to pay taxes on interest earned through high APY accounts?
Yes. The Internal Revenue Service (IRS) classifies any savings yield or CD compounding distributions as taxable interest income. At the beginning of each calendar year, your bank will issue an official **Form 1099-INT** detailing total dollar yields earned if they exceed $10. You must report this passive income on your federal tax filings unless the funds reside within tax-sheltered accounts like an IRA or 401(k).
What is the practical difference between APR and APY?
While both terms represent annualized financial percentages, they serve entirely different sides of banking transactions: **APR (Annual Percentage Rate)** measures the total cost you pay to borrow money (such as loans, mortgages, and credit cards), including upfront underwriting fees. **APY (Annual Percentage Yield)** measures the compounding wealth return a bank pays you for saving and investing capital. You want borrowing APRs low and saving APYs high! Learn more in our definition of What is APR (Annual Percentage Rate).
