What is Discretionary Income?
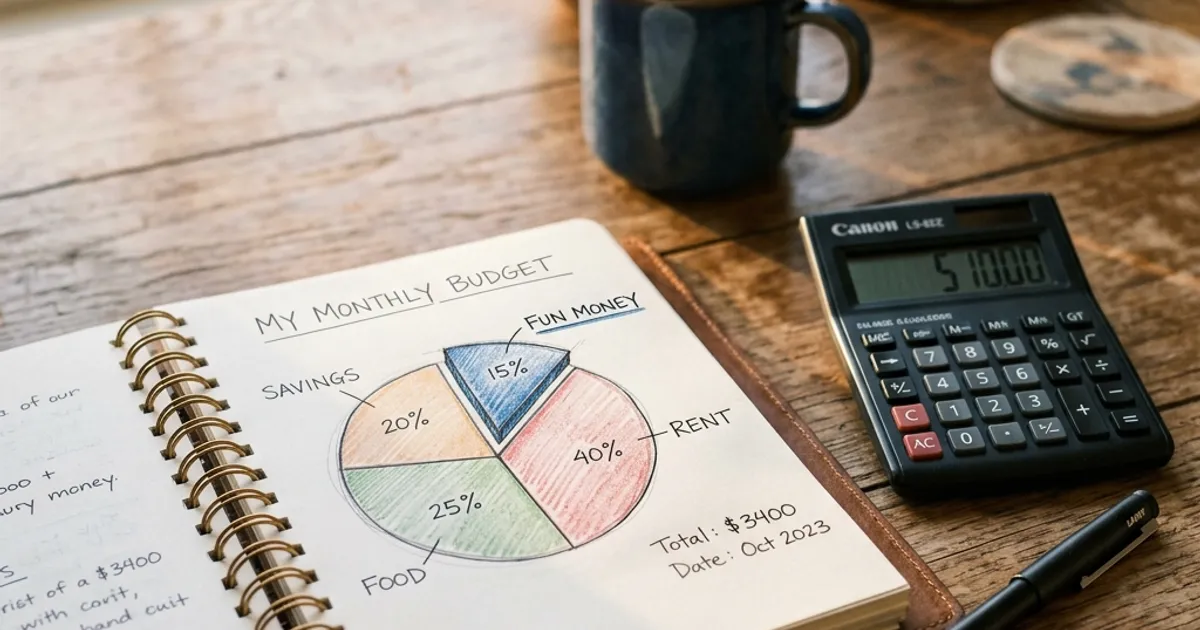
Discretionary Income is the money you have left over to spend, save, or invest after you have paid all your income taxes and mandatory living expenses (like rent, food, and utilities). It is essentially your "fun money" combined with your savings potential.
How to Calculate It
The formula is straightforward: Gross Income - Taxes - Essential Bills = Discretionary Income.
For example, if you earn $5,000 a month before taxes, the government might take $1,000 for taxes. That leaves you with $4,000 (your disposable income). If your rent, basic groceries, car payment, and utilities cost $2,500, you subtract that as well. The remaining $1,500 is your discretionary income.
You can use a Standard Budget Calculator to quickly find this exact number based on your personal expenses.
✔ Disposable vs. Discretionary
People often confuse these two terms, but they are very different:
- Disposable Income: Your paycheck after taxes are deducted. You still have to pay rent and buy groceries with this money.
- Discretionary Income: What is left after all taxes and basic survival needs are met. This is the money you actually have control over.
Why It Matters for Your Budget
If you follow the popular 50/30/20 budgeting rule (which you can track with our 50/30/20 Calculator), your discretionary income makes up the "30% Wants" and "20% Savings" categories combined.
A common trap for young professionals is letting their essential expenses grow too high. If you rent a luxury apartment and finance an expensive car, your mandatory bills eat up your entire paycheck. This leaves you with zero discretionary income, which directly leads to lifestyle creep and debt.
If you struggle to manage this leftover money, switching to Zero-Based Budgeting can help you assign every dollar a specific job before you accidentally spend it.
Frequently Asked Questions (FAQs)
Is a gym membership a discretionary expense?
Yes. While fitness is important for your health, a paid gym membership is not a mandatory survival expense like rent or basic groceries. It falls under discretionary spending.
What is a healthy amount of discretionary income?
Financial experts generally recommend keeping your mandatory needs under 50% of your take-home pay. This leaves the remaining 50% as discretionary income to split between savings, investments, and personal hobbies.
