What is Net Worth? (How to Calculate Your True Financial Freedom in 2026)
In personal finance and wealth management in 2026, your net worth represents a highly accurate, unvarnished quantitative snapshot of your overall financial well-being. While everyday societal conversation idolizes high annual incomes or luxurious visible consumption, true accredited financial planners know that your salary simply reflects cash velocity, whereas net worth measures your surviving accumulated wealth. Simply defined, net worth is an accounting subtraction formula: take the real economic value of everything you own (Total Assets) and subtract the comprehensive sum of everything you owe to creditors and banks (Total Liabilities). Here is how to audit your true balance sheet and transition from income dependency to lifelong financial independence.
⚡ Action Checklist: 4 Disciplined Habits to Skyrocket Net Worth
Do not let high monthly income deceive you into lifestyle creep. Apply these four net worth growth rules:
- ✔Track Your Balance Sheet Quarterly, Not Daily: Review your Net Worth Calculator ledger once every three months; obsessing over daily stock market volatility leads to emotional investing mistakes.
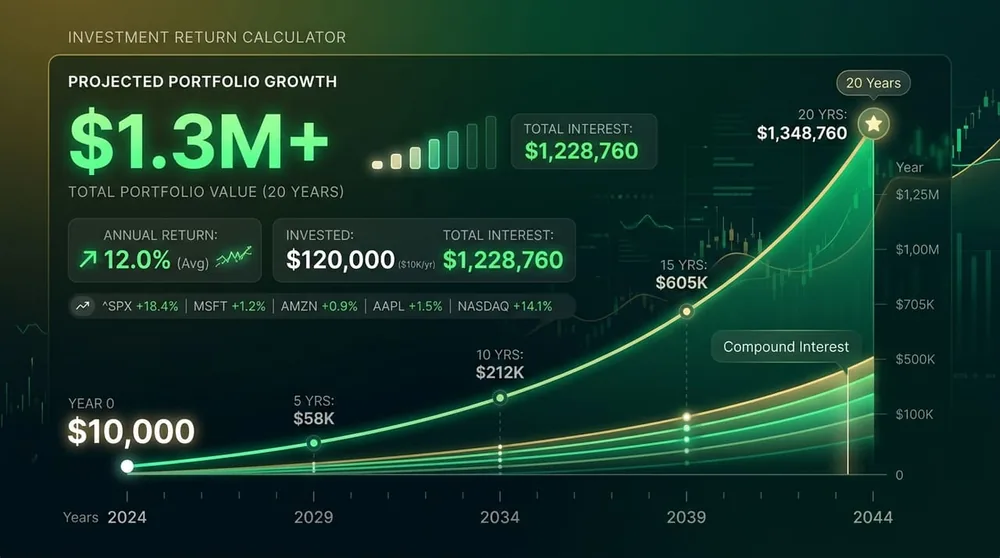
- ✔Prioritize Acquiring Appreciating Assets: Allocate your monthly cash surplus into assets that gain intrinsic compounding value over time—such as total market index funds, rental real estate, and high APY savings accounts.
- ✔Avoid Depreciating Financed Consumption: Never borrow money at high APRs to buy fast-depreciating consumer liabilities (like luxury automobiles or designer jewelry) that destroy your balance sheet.
- ✔Maximize Tax-Sheltered Account Contributions: Shelter your growing wealth from annual income tax erosion by maximizing contributions into 401(k)s, Roth IRAs, and Health Savings Accounts (HSAs).
1. Deconstruct Your Balance Sheet: Assets vs. Liabilities
To compute an accurate net worth figure without falling prey to self-deceptive inflation, you must strictly categorize financial items using institutional accounting definitions:
**Total Assets (Positive Wealth):** Items that possess verified liquid conversion value or generate economic revenue. This includes cash sitting in checking or high-yield savings accounts, retirement brokerage portfolios (401k, Roth IRA), individual stocks and treasury bonds, certified market resale equity in physical real estate, and formal business ownership stakes. Avoid listing fragile consumer items like furniture or wardrobes as valid wealth assets!
**Total Liabilities (Debt Commitments):** Every single dollar of outstanding contractual obligations you owe to external creditors. This includes your remaining mortgage loan principal, auto financing payoffs, student debt installments, open personal medical bills, and revolving credit card balances. According to educational wealth literacy resources from the Consumer Financial Protection Bureau (CFPB), minimizing uncollateralized consumer liabilities is the essential prerequisite to long-term economic resilience.
📊 Real-Life Case Study: High-Income Trainee vs. Frugal Saver
To understand why annual salary never equals wealth in 2026, examine two professionals working in the same city: Dr. Harrison (who earns $350,000/year) versus Maria (who works as an educator earning $72,000/year). Let's audit their genuine Net Worth balance sheets:
Dr. Harrison ($350k Salary)
• Assets: Luxury Condo ($800k) + Cash ($25k) + 401k ($100k) = $925,000
• Liabilities: Mortgage ($750k) + Med School Debt ($220k) + Luxury Auto Loan ($65k) = -$1,035,000
• Net Worth Calculation: -$110,000 (Insolvency!)
Maria ($72k Salary)
• Assets: Paid-Off Condo ($280k) + Cash ($30k) + Index Fund IRA ($210k) = $520,000
• Liabilities: Zero Credit Cards ($0) + Small Student Loan ($8k) = -$8,000
• Net Worth Calculation: +$512,000 (Half a Millionaire!)
Takeaway: Despite earning nearly five times less annual income, Maria holds half a million dollars in true economic wealth, whereas Dr. Harrison remains trapped in negative net worth due to heavy borrowing liabilities!
2. Total Net Worth vs. Liquid Net Worth
When banking institutions process commercial underwriting applications or assess financial retirement security, they segregate your balance sheet into two analytical variants:
- Total Comprehensive Net Worth: Includes all tangible and intangible economic items, featuring illiquid property real estate equity, vehicle trade-in valuations, and long-term retirement accounts. While comforting on paper, total net worth cannot be deployed immediately to meet emergency cash demands without selling physical real estate or triggering severe tax withdrawal penalties.
- Liquid Net Worth: Strictly isolates capital that can be converted into spendable cash within 24 to 48 hours without suffering severe market discount erosion. Liquid net worth encompasses checking accounts, High-Yield Savings Accounts (HYSAs), money markets, and standard brokerage index fund portfolios.
Evaluate your household liquid protection using our free Emergency Fund Savings Calculator, or learn how passive investing fuels balance sheets in our definition of What is a Total Market Index Fund.
Frequently Asked Questions (FAQ)
Is it normal to have a negative net worth when starting out?
Absolutely! Having a negative net worth in your twenties or early thirties is extremely common in the modern US economy, primarily driven by investments in higher education (student loan liabilities) or early household formation before peak earning decade arrives. As long as you maintain a high savings rate and systematically execute debt paydown strategies like the Debt Snowball or Avalanche, your net worth trajectory will quickly cross zero and begin compounding exponentially!
Should I include my primary family home in my net worth calculation?
Yes, but only your genuine **Home Equity**—meaning your property's realistic current conservative market resale price minus your outstanding mortgage loan principal balance and closing agent commissions. For conservative retirement planning, many wealth managers recommend calculating a secondary net worth figure that completely excludes your primary residence, because you will always need a shelter to live inside during retirement!
What is a good target net worth by age in 2026?
A classic rule of thumb coined by financial economists is the **Wealth Accumulating Formula**: multiply your current age by your total pre-tax annual household income, then divide that sum by 10. For instance, a 40-year-old earning $100,000 per year should aim for an accumulated baseline net worth of around **$400,000** (40 × $100,000 ÷ 10) to remain on a comfortable path toward financial independence.
